
Car-Buying Credit Prep: Reports, Budget and Loan Offers
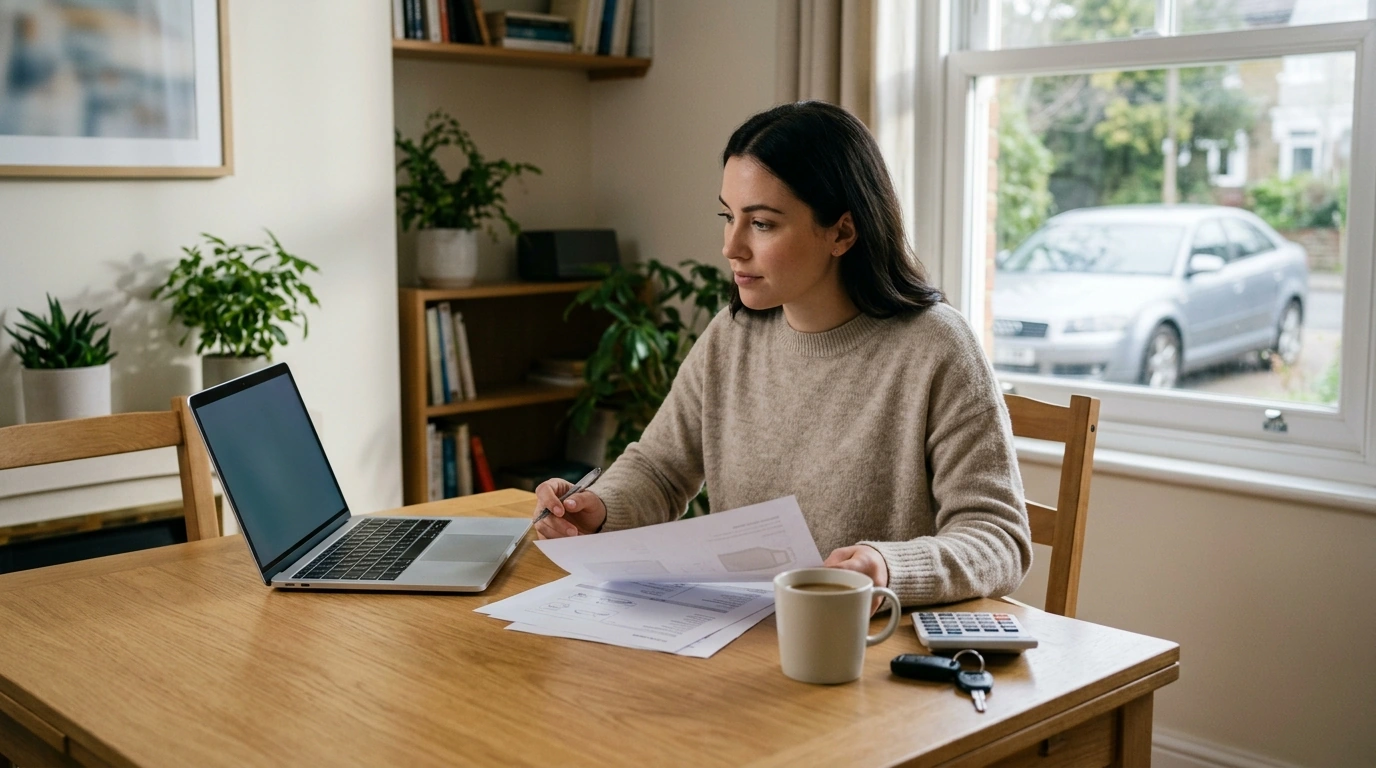
Car-Buying Credit Prep: Reports, Budget and Loan Offers
Start with your credit reports, not a score target
Get your reports from the major credit bureaus through AnnualCreditReport.com. Review each one for unfamiliar accounts, incorrect balances, and payments marked late that you made on time. An error is worth addressing even if you do not know exactly how correcting it will affect your score.
If you find a mistake, dispute it with the bureau reporting it and, when appropriate, the company that supplied the information. Keep copies of your supporting records and allow time for an investigation. The Consumer Financial Protection Bureau’s dispute guidance explains the process.
Do not build your plan around a number shown in one app. An auto lender may use a different scoring model, and your score can change as account information updates. Accurate reports and steady habits are more dependable goals than a promised point increase.
Choose credit moves you can keep up
Pay bills by their due dates and, where possible, reduce credit card balances relative to their limits. Avoid running those balances back up while you prepare to apply.
Think before opening or closing an account. A new application may produce a hard inquiry; closing a card can reduce your available credit. We would weigh either decision against the account’s costs and its place in your finances, not make it solely for a hoped-for score change.
- Several weeks or more before shopping: Review reports and start addressing errors.
- Each billing cycle: Pay on time and work down card balances where you can.
- Before applying: Set your car budget and prepare to compare loan offers.
Featured in this guide
Smart Strategies to Boost Your Credit Before Buying a Car – eBook Guide for Improving Your Credit Score
Budget for owning the car, not just buying it
Start with a monthly amount that leaves room for the rest of your life. Then estimate insurance, taxes, registration, fuel or charging, maintenance, and repairs. Set aside room for costs that arrive unevenly, such as tires.
A larger down payment can reduce what you borrow, but avoid draining your emergency fund to make a payment look manageable. There is no universal dollar rule that makes a car affordable; test the full cost against your own income and savings.
Compare offers before you commit
Consider seeking preapproval from a bank or credit union before discussing dealership financing. Compare each offer’s annual percentage rate (APR), term, amount financed, and total payments—not just its monthly payment. Use the same down payment and a similar amount financed when comparing offers.
A longer term may lower the monthly bill while increasing total interest and extending how long you owe money on the car. If you plan to apply with multiple lenders, review current guidance on how the timing of auto-loan inquiries may affect your credit.
If a demo vehicle makes your shortlist, our Is a Demo Car Worth Buying guide can help you prepare questions about its condition, warranty, and price.
Make your preparation usable
Use our credit-preparation eBook alongside your reports, budget, and lender quotes. Write down errors to address, payment due dates, and when you plan to compare offers. Give account updates and disputes time; no guide can guarantee approval, a particular rate, or a 100-point score increase.
When you shop, bring your budget and competing offers. You can then discuss the car’s price on its own merits before deciding whether the loan terms work for you.
Before choosing, compare the product details with your daily routine, available space, care needs, and preferred setup. The strongest option is usually the one that fits the intended use clearly and remains simple to clean, store, and check before repeat use.
FAQ
How to boost credit before buying a car?
Review your credit reports for errors, pay bills on time, reduce credit card balances where possible, and avoid unnecessary new applications while preparing. Compare loan offers as well as monitoring your credit.
What is the $3000 rule for buying cars?
There is no universal $3,000 rule that makes a car purchase affordable. Decide what you can spend using your own budget, including the down payment, financing costs, and ongoing ownership expenses.
How to raise credit score 100 points in 30 days?
No legitimate method can guarantee a 100-point increase in 30 days. Correcting a significant reporting error or lowering high card balances may help some people, but the result depends on their full credit file and when information updates.
See if Smart Strategies to Boost Your Credit Before Buying a Car – eBook Guide for Improving Your Credit Score fits your setup



Leave a comment