
From Scarcity to Financial Calm: A Practical Guide
15% off on product page · save $1.06
From Scarcity to Financial Calm: A Practical Guide
What a Scarcity Money Mindset Looks Like
Financial scarcity may describe an actual shortage of money. A scarcity mindset is the mental state that develops when the possibility of not having enough dominates attention. That sense of danger can continue even after income, savings, or circumstances improve.
Common signs include repeatedly checking balances, avoiding bills, feeling guilty about reasonable purchases, hoarding supplies, comparing finances with others, or acting quickly because an opportunity appears unlikely to return. Scarcity can narrow attention to the most urgent expense. Although that focus may help during an immediate crisis, it can make planning for annual bills and long-term priorities more difficult.
This mindset is not a character flaw. It can develop after unstable income, debt, job loss, childhood hardship, or emergencies that made security feel temporary.
Scarcity Patterns and Calmer Alternatives
| Scarcity-driven pattern | Possible effect | Calmer alternative |
|---|---|---|
| Avoiding account balances | Uncertainty and missed deadlines increase | Schedule one brief weekly check-in |
| Buying immediately because a deal may disappear | Spending becomes reactive | Pause for 24 hours on nonessential purchases |
| Saving without a defined purpose | Any spending may feel unsafe | Create named funds for emergencies and goals |
| Focusing only on the next bill | Irregular costs remain surprising | List quarterly and annual expenses |
| Treating every setback as failure | Shame encourages avoidance | Review the event and adjust one part of the plan |
Featured in this guide
From Scarcity to Financial Calm: A Practical Guide to Overcoming a Scarcity Money Mindset
Separate Real Limits From Fear-Based Assumptions
Begin with facts rather than reassurance. Record current income, required expenses, minimum debt payments, available cash, and upcoming obligations.
Then distinguish a present constraint from a predicted catastrophe. This bill is due Friday identifies a problem that can prompt action. I will never be secure is a broad conclusion to examine rather than accept as fact.
Use neutral, specific language. Replace I am terrible with money with I missed two due dates and need a reminder system . A defined issue is easier to address than an identity-based judgment.
If available resources cannot cover essential needs, mindset work alone is insufficient. Contact creditors, ask about hardship programs, investigate public benefits, or consult a reputable nonprofit counselor.
Create a Weekly Money Ritual
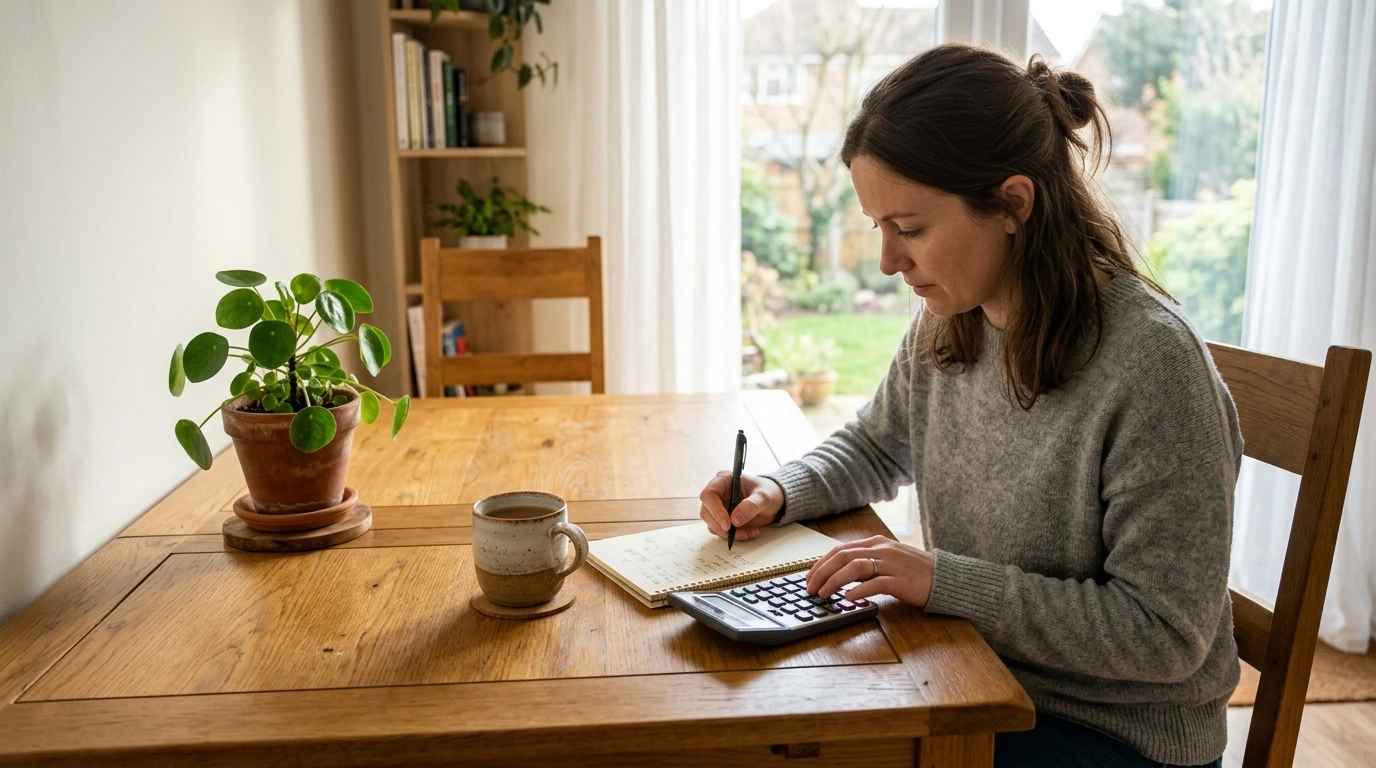
Hold a consistent 15-minute review. Check balances, recent transactions, bills due, and one upcoming expense. A short session can reduce avoidance without turning money management into an exhausting project.
Choose one stabilizing priority at a time: catch up one account, begin a small emergency buffer, cancel an unused subscription, or automate a minimum payment. For nonessential purchases above a personal threshold, consider a 24- or 48-hour waiting period.
Keep evidence of capability. Record bills paid on time, purchases declined, savings contributions, and issues handled early. These moments can challenge the belief that financial control is impossible.
Build Systems That Make Calm Easier
Separate money into clear categories for bills, daily spending, emergencies, and predictable future costs. Whether those boundaries live in different accounts or budget categories, they reduce the need to reconsider every dollar.
Automate carefully. Align payment and transfer dates with income timing, and maintain enough room in the relevant account to reduce overdraft risk. Include a realistic amount for enjoyment as well; excessive restriction can contribute to impulsive spending followed by regret.
Define what enough means for the current stage of life. It may mean essential bills are paid, minimum debt obligations are covered, a starter emergency fund is growing, and modest progress is being made toward one goal.
Use Guided Resources With a Real-World Routine
From Scarcity to Financial Calm: A Practical Guide to Overcoming a Scarcity Money Mindset can be paired with weekly reviews, a simple spending plan, and brief written reflections about recurring triggers.
Look for practical signs of progress: fewer avoided bills, longer pauses before unplanned purchases, clearer purposes for savings, and less distress during routine financial tasks.
Check the listed dimensions for use guided resources with a real-world routine against the available vehicle space before use.
When Additional Support May Help
Consider professional support when financial fear disrupts sleep, relationships, work, eating, or necessary spending. A qualified mental health professional can help address anxiety, trauma, or compulsive behavior connected with money.
For debt and repayment guidance, seek transparent nonprofit credit counselors who explain their fees, credentials, services, and alternatives before requesting a commitment.
Financial calm is not the absence of difficulty. It is the capacity to face the facts and choose the next reasonable action.
Check the listed dimensions for when additional support may help against the available vehicle space before use.
Compare related options such as Boost Your Confidence Toolkit: Speak Boldly Guide, Confidence Checklist & Self-Esteem eBook to match features, dimensions, and use case before choosing.
FAQ
What does financial scarcity mean?
Financial scarcity can mean an actual shortage of resources or the mental pressure created by expecting there will never be enough. Real constraints and learned fear can exist at the same time.
What is the 7 7 7 rule for money?
There is no single, universally recognized 7 7 7 money rule; the phrase is used for several budgeting, saving, and investing approaches. Review the specific definition and its risks before following any version.
Do rich people have a scarcity mindset?
Yes. Income and wealth do not automatically eliminate scarcity beliefs, and people with substantial resources may still fear spending, obsess over losses, or feel unsafe because of past experiences or anxiety.
See if From Scarcity to Financial Calm: A Practical Guide to Overcoming a Scarcity Money Mindset fits your setup



Leave a comment